Case Study
The site
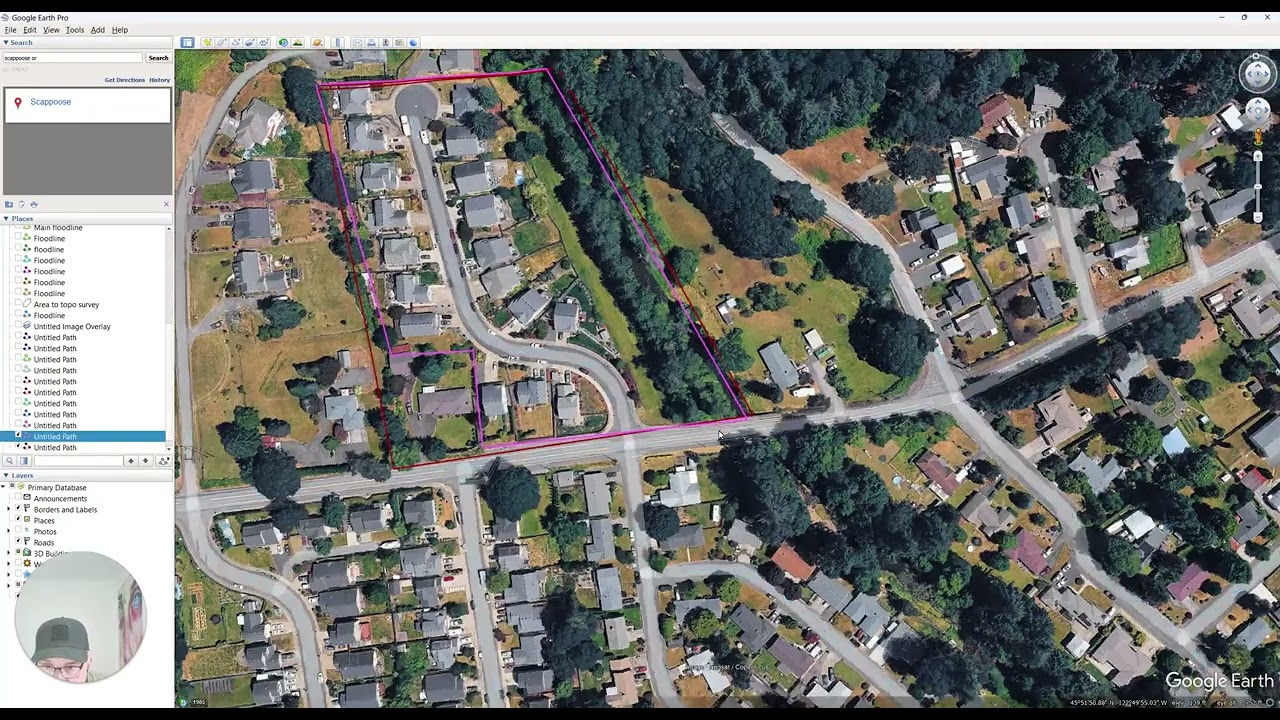
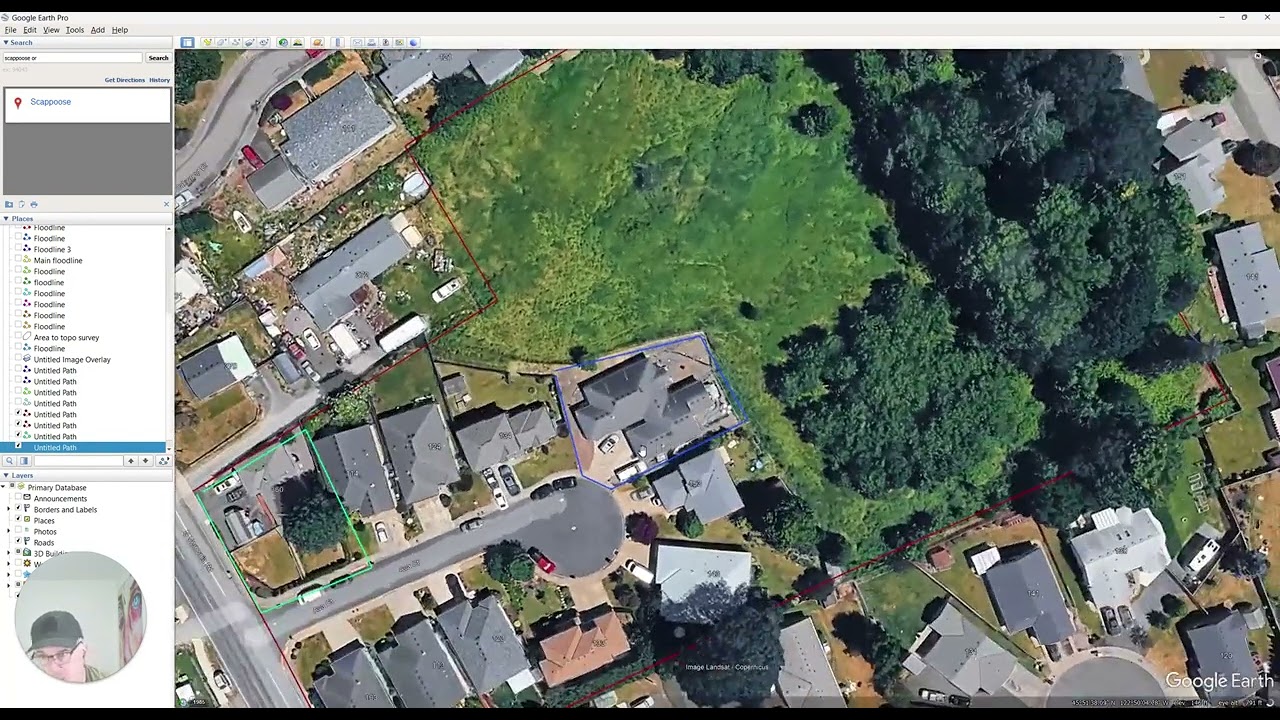
A parcel at the end of a residential street in a fast-growing Oregon town inside the Portland metro tech corridor. Close to the Nike, Intel, and Adidas headquarters. A short drive to downtown. Flat land, good drainage, all utilities at the property line, existing streets on every side.
The town has a strong school system and is in serious housing undersupply — the market needs roughly 1,200 housing units. Almost nothing is on the market in the affordability range buyers want.
The deal
We bought the parcel, took it through entitlements, brought in a partner, repositioned the project, and sold our position before any vertical construction started. From acquisition to exit, our cash exposure peaked at about $35,000.
We sold our position for $400,000.
The original entitlement
We bought the parcel for around $203,000 with seller financing — owner-carried contract, no bank loan at acquisition. Then we entitled it as a tiny home project.
Oregon had just rolled out new tiny home code and we got the parcel approved for two clusters of six units each. 12 tiny homes total.
Total cash into entitlement work: about $30,000–$35,000.
The pivot
Once we had entitlements and started construction drawings, the tiny home math changed. The code wanted parking, infrastructure, and site improvements that weren't in the original numbers. The deal still penciled, but not as well as it had on paper.
We re-evaluated. Townhomes were a better fit for the parcel.
Re-entitled the project for 16 townhomes. Same parcel, more units, cleaner economics.
The partner structure
After the initial entitlement, we replaced the seller financing with a hard money loan and brought in a capital partner. The partner contributed $200,000.
That capital reimbursed our entitlement spend and bought out our seller-carried position. We were now ahead about $165,000–$170,000 in the deal with no money out of pocket.
The exit
The partner wanted to go vertical. We didn't. Our highest and best use of capital was the next deal, not 16 townhome builds on this one.
We told the partner we were thinking about selling our position. He said: we'd rather buy you out and keep going.
We agreed on $200,000 for our remaining position.
The numbers
Acquisition: ~$203,000 (seller-carried, no cash at close)
Entitlement spend: ~$30,000–$35,000
Peak cash exposure: ~$35,000
Initial partner buy-in: $200,000 (covered our entitlement spend, took us ahead)
Final buyout from partner: $200,000
Total proceeds: ~$400,000
Interest carrying costs: ~$30,000
Net to us: ~$325,000
Time in deal: under 18 months
Vertical work performed: zero
Why this matters to an investor
Three things about Elm Street are worth understanding.
1. Entitlements are the highest-margin work in development.
We turned $35,000 into $325,000 net by doing one thing — moving a parcel from raw land to fully entitled lots. No foundations, no framing, no horizontal construction beyond planning. The value we added was paperwork and engineering. That's the cleanest margin in this business and it's available on every deal we do.
2. The right pivot beats the original plan.
We had the parcel entitled for tiny homes when the math shifted. Most developers stay committed to the entitlement they paid for because they don't want to spend the money to re-entitle. We did. The townhome entitlement made the parcel more valuable to a vertical-focused buyer than the tiny home entitlement would have. The re-entitlement spend paid for itself many times over in the buyout.
3. Know when to sell your position.
Our partner wanted to go vertical. We didn't. He valued the parcel at vertical-build math. We valued our time at next-deal math. The buyout cleared the disagreement and let both sides do what they wanted to do.
The right time to exit a deal is when someone else values your position more than you do. He's going to do well on the vertical build. We did well on the entitlement. Both sides win.
In short
Entitlements are the highest-margin work in development. Sell your position when someone else values it more than you do.
— Joe Kessi, CEO Fidelis First